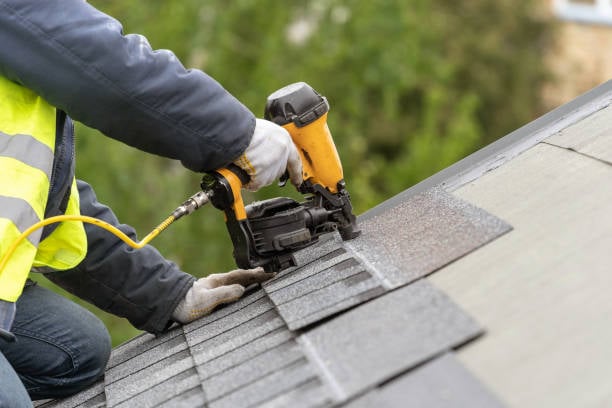
Fort Worth Home Insurance: Why Roof Age Matters Before You Buy
Education Kemberly McLaughlin September 3, 2026
Education Kemberly McLaughlin September 3, 2026
Picture two Fort Worth homes listed at $440,000.
Both have three bedrooms. Both are approximately 1,900 square feet. Both offer a reasonable commute to the airport.
One is a Grapevine home with an older roof. The other is a newer home in Roanoke with a roof installed last spring.
On a listing sheet, they may appear comparable. Send both addresses to several independent insurance brokers, however, and the difference may become clear very quickly.
The homes may qualify for different carriers, deductibles, premiums, inspection requirements, and roof-loss settlement terms. Depending on the roof’s age and condition, one may qualify for replacement-cost coverage while the other receives only actual-cash-value coverage for the roof. Some carriers may decline to write the older roof at all without an inspection or replacement.
That difference has little to do with bedroom count, school boundaries, or curb appeal. It begins with one detail buyers do not always ask about early enough:
When was the roof installed, and how will the insurance company cover it?
Roof age has always been part of a homeowners insurance application. In today’s Texas insurance market, it has become increasingly important.
There is no single statewide rule requiring every insurance company to treat a roof differently at exactly 15 or 20 years. Each carrier establishes its own underwriting guidelines. The roof’s material, documented installation date, visible condition, prior claims, and resistance to wind and hail can all affect the decision.
Still, buyers should expect coverage choices to narrow as a roof ages. Depending on the carrier, an older roof may result in:
A roof can still appear serviceable during a general home inspection while creating an insurance issue. A home inspector evaluates its visible condition. An insurance underwriter decides whether the company is willing to assume the financial risk.
Those are related questions, but they are not the same question.
A policy may say that wind and hail are covered without telling the full story. Buyers also need to understand how the insurance company will calculate a roof claim.
Replacement-cost coverage generally pays the cost to repair or replace covered property with comparable materials, subject to the deductible and policy limits.
For roof claims, the insurer may initially pay the roof’s actual cash value and release recoverable depreciation after the work is completed and documented. Buyers should ask the agent to explain the exact claim process for the proposed policy.
Actual cash value subtracts depreciation based on factors such as the roof’s age and condition.
The Texas Department of Insurance provides an example in which a 10-year-old roof has an actual cash value of $7,000. With a $2,000 deductible, the policy would pay $5,000 toward the covered loss.
If replacing that roof costs substantially more, the homeowner is responsible for the remaining amount.
Both policies may cover hail. They do not necessarily produce the same claim payment.
Fort Worth is not one housing market with one construction era. Buyers may compare homes built nearly a century apart within the same price range.
Fort Worth area or housing era | Roof question to investigate | Possible insurance consideration |
|---|---|---|
Fairmount and Arlington Heights | When was the current roof installed, and is the date documented? | An older structure can still qualify well with a recent roof. An aging roof may reduce carrier and coverage choices. |
Ridglea, Wedgwood and other mid-century neighborhoods | Has the roof been replaced recently, or is it approaching another replacement cycle? | Coverage may depend more on the current roof than the original age of the house. |
1980s and 1990s suburban construction | Is the roof original, a later replacement, or part of a prior storm claim? | Some homes may have roofs old enough to trigger inspections, ACV terms, or replacement requirements. |
Walsh, Alliance-area communities and newer North Fort Worth construction | What roofing material was installed, and does it qualify for an impact-resistance credit? | A newer roof generally provides more underwriting options, but the premium still depends on the home, buyer, carrier, location, and coverage selected. |
An older neighborhood does not automatically mean higher insurance costs.
A 1930s bungalow with a properly documented roof installed two years ago may offer better roof coverage than a newer suburban home with an aging replacement roof. The house’s construction year and the roof’s installation year are two different facts.
After confirming how the roof is covered, look at the deductible.
Texas homeowners policies may carry a separate wind and hail deductible. Unlike a flat-dollar deductible, it may be stated as a percentage of the home’s insured dwelling value.
If a home is insured for $400,000:
Wind and hail deductible | Homeowner’s portion of a covered claim |
|---|---|
1% | $4,000 |
2% | $8,000 |
3% | $12,000 |
That percentage is generally applied to the dwelling coverage amount, not the estimated cost of the repair.
A 2% deductible does not mean the homeowner pays 2% of a $20,000 roof replacement. On a home insured for $400,000, it means the homeowner is responsible for the first $8,000 of the covered loss.
Now combine that deductible with actual-cash-value roof coverage. The homeowner may face both a significant deductible and depreciation deducted from the claim payment.
That is why two similarly priced homes can carry very different financial exposure after a hailstorm.
The list price tells you what the seller is asking. The insurance quote helps tell you what the home may cost to own.
The larger insurance market provides important context.
Texas Department of Insurance rate-filing data shows average statewide homeowners rate changes of:
The 2025 increase was smaller, but it followed two years of substantial increases.
The Federal Reserve Bank of Dallas also reported that the median Texas homeowner paid approximately 60% more for home insurance in 2024 than in 2019. Nationally, the increase during that period was approximately 30%.
The Dallas Fed identified weather exposure, construction costs, labor costs, and reinsurance expenses among the pressures affecting Texas premiums. It also found that Dallas-Fort Worth had one of the state’s highest insurance burdens.
Rates may be rising more slowly than they did two years ago, but that does not mean buyers can safely estimate insurance from a previous home, a neighbor’s policy, or a general online calculator.
The property and the buyer both matter.
Impact-resistant roofing can strengthen a home’s insurance position, particularly in a hail-prone market.
Roofing products are generally classified from Class 1 through Class 4 based on recognized impact-resistance testing. Class 4 represents the highest rating within that system.
The Texas Department of Insurance states that qualifying impact-resistant roofing materials may receive a premium credit. The amount is not universal. Each insurance company determines:
A seller’s statement that the home has “impact-resistant shingles” may not be enough. Buyers should request the product information, roofing invoice, warranty, installation records, and any applicable certification form.
If the roof qualifies, the policyholder may need to submit that documentation before the insurer applies a credit.
Buyers should also ask whether accepting the discount affects coverage for cosmetic hail damage. Some endorsements may limit coverage when hail dents or marks a roof without affecting its ability to function.
A discount is helpful only when the buyer understands the coverage attached to it.
Insurance does not need to be the last financial question answered before closing.
When comparing Fort Worth homes, ask:
Before making an offer, buyers can contact their insurance broker for preliminary guidance about the address, roof age, claims environment, and likely coverage concerns.
A complete quote may require additional information about the buyer and property. Once under contract, it should be requested as early in the option period as possible.
That timing gives the buyer an opportunity to investigate an unexpectedly high premium, obtain additional quotes, review the roof more closely, or discuss possible solutions with the seller while contractual options remain available.
Waiting until the week of closing leaves fewer choices.
A resale home and a new build should not be compared by price and mortgage payment alone.
A complete ownership comparison may include:
A newer home may begin with a newer roof and broader insurance options. That does not automatically make it the better financial decision. New construction can bring different tax assessments, community fees, lot premiums, or commute considerations.
The goal is not to direct every buyer toward the newest roof. It is to make sure the older roof is priced and insured with open eyes.
No.
A recently replaced roof on a historic Fort Worth home may qualify for replacement-cost coverage. The carrier will consider the current roof, its material and condition, the available documentation, and the rest of the property’s underwriting profile.
The age of the house does not automatically determine the roof coverage.
No.
A new roof may improve the number of available carriers and coverage options, but insurance pricing also considers replacement cost, square footage, construction type, location, fire protection, claims history, credit-based insurance information where permitted, deductibles, and selected coverage limits.
Newer does not guarantee cheapest. It often means fewer roof-age complications at the beginning.
Any solution should be structured through the purchase contract and reviewed with the buyer’s lender, insurer, title company, and real estate professionals.
Depending on the property and transaction, the parties might discuss roof replacement before closing, a price adjustment, allowable seller concessions, or another negotiated solution. Lender and insurance requirements can limit what is practical.
A credit does not solve the problem if the insurance company will not bind acceptable coverage on the roof as it currently exists.
Buyers who are surprised by an insurance quote are not necessarily careless. Most listing portals train us to compare price, square footage, photographs, and estimated monthly payments first.
Insurance underwriting uses a different set of questions.
In Fort Worth, the roof’s installation date, coverage basis, and wind and hail deductible can materially change the cost and risk attached to a home. Those details deserve attention before the option period is nearly over and well before the closing table.
If you are comparing a Fort Worth resale with new construction, Silver Elk Realty can help you examine the full ownership picture, not simply the list price. Bring us the addresses, and we will help you identify the property questions to ask your insurance professional early enough for the answers to matter.
Schedule a consultation with Silver Elk Realty.
Stay up to date on the latest real estate trends.
Education
The Questions to Research Before Making an Offer
Development
Education
Understanding Foundation Reports and Options
Lifestyle
Mira Vista Country Club's Renovation: What Actually Changed for Residents
Lifestyle
Local Chefs Lead The Way
Lifestyle
Mira Vista's Lifestyle Choices Have Expanded
Lifestyle
Experience a seamless real estate journey backed by a dedicated team focused on your success.